USPAP CERTIFIED
Gift Tax Appraisal
Gift tax valuation services for Form 709 filings, family business transfers, and gifted minority interests, prepared in accordance with USPAP. Gift Tax Appraisal values closely held business interests, family limited partnerships, LLC membership units, and fractional ownership stakes for gifting transactions nationwide.
- USPAP-compliant valuations
- Family gifting & FLP/LLC interests
- Defensible, IRS-ready reports
What We Deliver
Business Valuation Services for Gift Tax Purposes
Gift Tax Appraisal prepares USPAP-compliant business valuations for lifetime gifting, family wealth transfer, and related estate planning purposes. Every engagement is tailored to the gifted interest and its intended use on your Form 709 filing.
Business Valuation for Gift Tax Reporting (Form 709)
USPAP-compliant valuations supporting federal gift tax filings, with fair market value conclusions prepared for IRS Form 709 reporting.
Family Business & FLP/LLC Interest Valuation for Gifting
Valuations of family limited partnership and LLC interests transferred as part of family gifting and wealth transfer strategies.
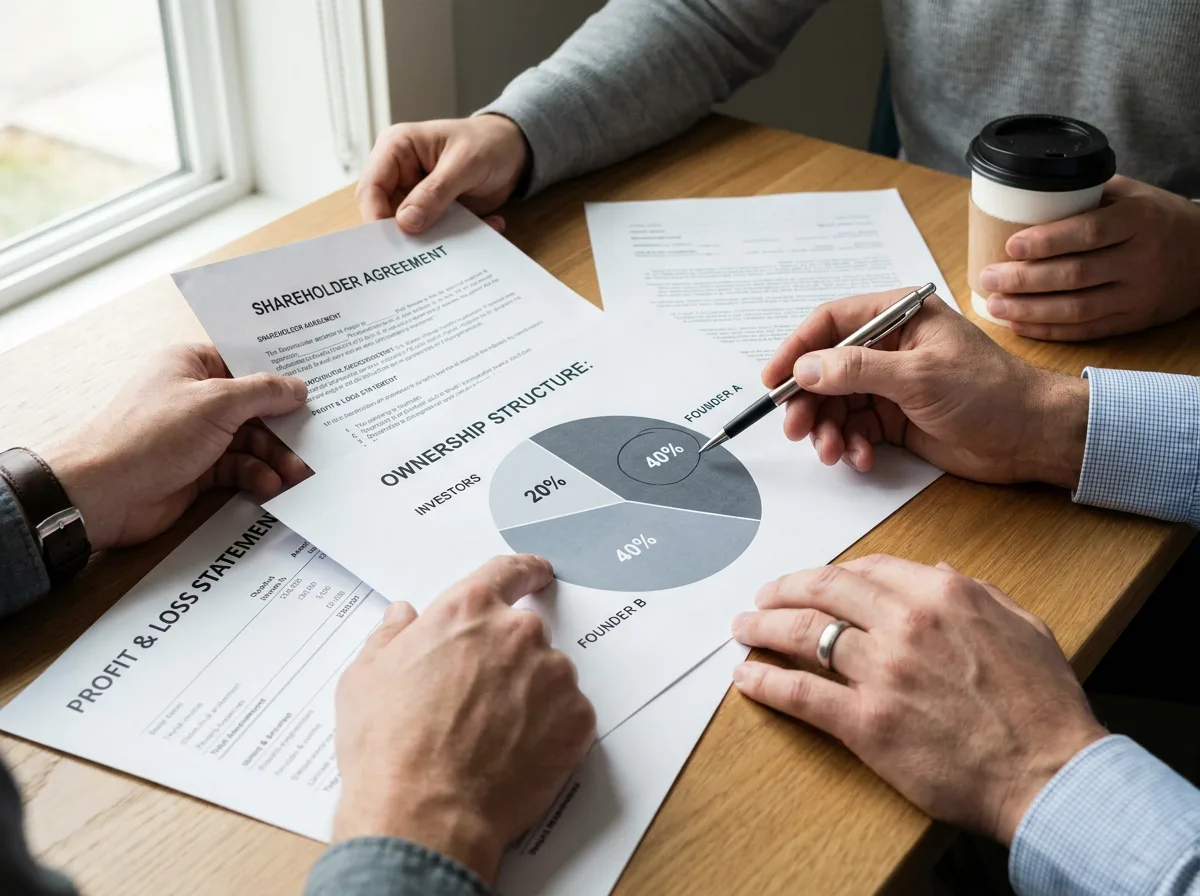
Minority & Fractional Interest Valuation for Gift Tax
Defensible valuations of non-controlling and fractional ownership stakes, incorporating marketability and control discounts where applicable.
Business Valuation for Related Estate & Trust Planning
Valuations supporting broader estate and gift tax planning, including trust funding, generation-skipping transfers, and succession strategies tied to lifetime gifting.
Four Steps to Your Report
How Our Gift Tax Valuation Process Works
- 01
Submit Your Information
Provide details about the business or interest being gifted, the ownership structure, and your Form 709 filing timeline.
- 02
Our Team Conducts the Analysis
Our appraisers gather financial data, apply recognized valuation methodologies, and evaluate any applicable marketability or control discounts.
- 03
We Prepare Your Report
Your USPAP-compliant valuation is documented with detailed findings, discount support, and the fair market value conclusion a qualified appraisal requires.
- 04
Report Delivered
You receive a defensible valuation ready to support your gift tax return, estate plan, or related filing.
Get Your Gift Tax Valuation Started
Our USPAP-compliant valuations are prepared to meet IRS Form 709 requirements and support family gifting, FLP/LLC transfers, and related estate planning. Start with a consultation to discuss your gifted interest and filing deadline.
Resources
Gift Tax Appraisal Insights
Guides on valuation discounts, FLP and LLC interests, and how the gift tax appraisal process works.
Gifting Real Estate to Family: How Tax Basis, Appraisals, and Form 709 Work Together
Gifting real estate to family members carries over the donor's tax basis instead of stepping it up, often leaving the recipient with a bigger capital gains bill than anyone expected. This guide walks through the carryover basis rules under IRC Section 1015, the dual-basis trap for depreciated property, and why a contemporaneous appraisal still matters for Form 709 reporting.
Read more →
Valuation Discounts for Estate and Gift Taxes on Closely-Held Interests and FLPs
Valuation discounts for estate and gift taxes reduce the pro-rata fair market value of closely-held business stock, FLP interests, and fractional ownership when reported on Form 706 and Form 709. This guide explains how DLOM and minority interest discounts are built, stacked, and documented so they hold up under IRS review.
Read more →
Gift Tax vs Estate Tax Appraisals: How Valuation Dates and Methods Differ
A gift tax appraisal is locked to the date the gift is made, while an estate tax appraisal can shift to an alternate date six months after death. This guide explains why that single difference reshapes valuation strategy, timing, and the appraisal itself.
Read more →
How to Report a Gift of Closely Held Stock or Business Equity on Form 709
Reporting a business equity gift on Form 709 takes more than writing a number on Schedule A: the entity description, the adequate disclosure statement, and the qualified appraisal all have to line up or the IRS statute of limitations never starts to run. This guide walks through the mechanics so the return holds up if it's ever reviewed.
Read more →
The Gift Tax Valuation Penalty: What Happens if You Underreport Value on Form 709
Filing Form 709 on time doesn't protect you from a gift tax valuation penalty if the number you reported turns out too low. This guide breaks down the 20% and 40% penalty tiers under IRC Section 6662, the $5,000 underpayment floor, and how a qualified appraisal supports a reasonable cause defense.
Read more →
What Triggers an IRS Audit of a Gift Tax Appraisal: Key Red Flags
Aggressive discounts, weak appraiser credentials, and undervalued closely held interests are the fastest ways to draw IRS scrutiny to a Form 709 valuation. This guide breaks down the specific triggers and the disclosure rule that decides whether the audit window ever closes.
Read more →
How Form 709 Establishes Gift Tax Basis and Starts the IRS Statute of Limitations
Filing Form 709 does more than report a taxable gift: a well-documented fair market value on the return can start the IRS's three-year assessment clock and shield that valuation from a later challenge. This guide explains gift tax basis under Form 709, the carryover basis rule, and why adequate disclosure depends on a defensible appraisal.
Read more →
Fair Market Value vs. Appraised Value: Why a Qualified Appraisal for Gift Tax Matters
A dealer letter or online price estimate is not the same as a qualified appraisal for gift tax reporting, and the gap between them can cost a donor penalties and an open-ended IRS audit window. This guide walks through what the appraisal must document to start the statute of limitations and avoid valuation penalties.
Read more →
How to Value a Minority Interest in a Family Business for Gift Tax Purposes
A minority interest gifted out of a family business is worth less than its pro-rata share, and the IRS agrees, within limits. This guide explains how the minority interest discount for gift tax works, what supports it, and how to report it correctly on Form 709.
Read more →
What Happens If You Don't File Form 709 When You Should Have
The penalty for not filing a gift tax return is often $0 if your gifts sit inside the lifetime unified credit, which surprises most people. The real cost is that the IRS's three-year window to challenge your gift's value never opens, leaving it exposed for decades.
Read more →
Discount for Lack of Marketability in Gift and Estate Tax Valuations
A discount for lack of marketability can shrink a gift or estate tax valuation by 20% to 50%, but only when the appraiser's methodology holds up to IRS scrutiny. This guide explains how DLOM is quantified, what ranges courts have accepted, and where the Tax Court has drawn the line.
Read more →
How Valuation Discounts Work in Gift Tax Appraisals for FLP and LLC Interests
Valuation discounts in gift tax appraisals can meaningfully reduce the taxable value of a gifted FLP or LLC interest, but only when the discount is properly supported and disclosed. This guide walks through DLOC, DLOM, Form 709 disclosure rules, and the case law that decides whether discounts hold up.
Read more →
FAQ
Frequently Asked Questions
How much does a gift tax valuation cost?
Gift tax valuations are quoted as a fixed fee after we review the business interest or asset being gifted, since cost depends on the complexity of the ownership structure and the completeness of available financial records. Contact us for a quote scoped to your specific gifting transaction.
How long does a gift tax valuation take?
Most business valuations are completed three to five weeks after we receive your financial documentation, with expedited delivery available in as fast as 11 business days for approaching Form 709 deadlines. Tell us your filing date and we'll confirm up front whether we can meet it.
What credentials do your appraisers hold?
Our appraisers hold credentials with leading organizations such as the ASA, AICPA (ABV), and CFA Institute. Every valuation is prepared in accordance with USPAP, so your report meets the standard expected of a qualified appraisal.
Do you value family limited partnership and LLC interests for gifting?
Yes. We value FLP and LLC interests, minority and fractional ownership stakes, and other closely held business interests commonly transferred in family gifting strategies, applying marketability and control discounts where appropriate.
Can you still help if my gift tax return is already due?
Yes. Tell us your filing deadline and we'll confirm up front whether we can meet it. Expedited delivery is available when a Form 709 deadline is approaching.
Get Started
Request a Business Valuation
Tell us about the business interest being gifted and your Form 709 filing timeline, and our team will follow up with a fixed-fee quote.